
Increase in solidarity contribution for company cars

Increase in solidarity contribution for company cars

When employees are allowed to use their company car for private purposes, the employer has to pay a CO2 solidarity contribution to the NSSO. As part of the “greening” of the vehicle fleet, this “CO2 contribution” will be increased as of 1 July 2023. Additionally, the tax deductibility of company cars will be reduced (for fully electric vehicles) and phased out (for cars with a combustion engine).

We will discuss the increase in the solidarity contribution for company cars ordered as from 1 July 2023 in this newsletter.

How is the solidarity contribution calculated now?

A formula is used to calculate how much the solidarity contribution amounts to. This formula differs depending on the fuel type of the vehicle.

The amount is then multiplied by the indexation coefficient, since an indexation takes place on 1 January of each year. The indexation coefficient for 2023 is equal to 1.5046.

The calculation looks as follows for the year 2023:

  • Diesel cars: [[(CO2 emission rate x € 9) – 600] / 12] x 1.5046;
  • Petrol cars: [[(CO2 emission rate x € 9) – 768] / 12] x 1.5046;
  • Gas-powered cars (LPG, CNG or methane): [[(CO2 emission rate x € 9) – 990] / 12] x 1.5046.

The minimum solidarity contribution is currently € 20.83 (indexed: € 31.34).

For electric cars, the minimum solidarity contribution is multiplied by the indexation coefficient. For the year 2023, this amounts to € 20.83 x 1.5046 = € 31.34.

What happens as of 1 July 2023?

A higher solidarity contribution will have to be paid on company cars purchased, rented or leased as from 1 July 2023. The order date mentioned on the order form is decisive. In case of leasing/rental, the date of the lease/rental agreement is decisive. The result of the calculation according to the abovementioned formula will be multiplied by a factor. This factor will increase as follows:

  • Multiplication by factor 2.25 from 1 July 2023 to 31 December 2024;
  • Multiplication by factor 2.75 from 1 January 2025 to 31 December 2025;
  • Multiplication by factor 4.00 from 1 January 2026 to 31 December 2026;
  • Multiplication by factor 5.50 from 1 January 2027.

Increased minimum contribution from 1 January 2025

The minimum solidarity contribution will also be increased. This increase will only take effect from 1 January 2025.

It is a non-indexed amount, with a minimum of:

  • € 23.41 from 1 January 2025;
  • € 25.99 from 1 January 2026;
  • € 28.57 from 1 January 2027;
  • € 31.15 from 1 January 2028.

These amounts are therefore yet to be indexed as indexation is not yet available for these dates in the future.

Exception for electric company cars

For electrically powered cars, the solidarity contribution is still calculated according to the abovementioned formula, without multiplying by a factor.

The minimum solidarity contribution does apply to electric cars, with the same minimum amounts as for non-electric cars.

The impact of this change is therefore quite limited for electric company cars and only noticeable as from 1 January 2025. For other types of company cars, the increase will already have an impact for company cars ordered starting from 1 July 2023.

Action point

! Provide your Payroll Business Partner with the date of the order form or the date of the lease agreement (if it is a lease) when you assign your employee a company car. This is essential for accurate payroll processing.
Student work: important points of attention 2023

Student work: important points of attention 2023

The summer holidays are just around the corner, so it is high time to outline the basic principles of student work.

Who is eligible for student work?

A student has to be at least 16 years old (15 years if he completed the first two years of secondary school) and has to follow a full-time training curriculum. Someone following an evening class is not considered eligible for student work.

A student finishing school in June and graduating, can work with a student contract until September 30 of the same year.

However, a student who terminates his/her studies during the academic year is no longer considered a student and can no longer enter conclude a student contract, even if he/she does not immediately receive his/her degree.

The student can work a maximum of 12 subsequent months.


Lower solidarity contribution for student work and quota of 600 hours

Under certain conditions, student work is exempt from normal social security contributions (ca. 28% for the employer and 13,07% for the student). Student work is subject to a much lower solidarity contribution (5,42% for the employer and 2,71% for the student), provided that the following conditions are met:

  • The student is employed in the framework of a written student agreement that contains certain legally mandatory provisions and is concluded prior to the start of the activities. The student contract is always a fixed-term contract (max. 12 months).
  • In our newsletter of 1 January 2023, you could read that students are allowed to work 600 hours per year from 1 January 2023 to benefit from the lower solidarity contributions (the quota of 600 hours). Previously, this annual limit was 475 hours. This measure is valid in the calendar years 2023 and 2024. In 2024, an evaluation will be made on whether to extend this new measure. If the student works more than 600 hours, the solidarity contribution is no longer applicable and regular social security contributions (as for a normal employee) will be due as from the 601st hour onwards. The student can consult the number of worked hours at Student@work. He or she can also download a certificate confirming the number of available hours of the quota. We highly recommend requesting this certificate in advance in order to be sure of the number of quota hours the student has left to work with the advantageous solidarity contribution.
  • The student is only allowed to work during periods he/she does not have to be present at school.
  • The employer has performed a specific Dimona declaration for students prior to the start of the employment. If you prefer your Payroll Business Partner to make this declaration, please inform him/her at least two working days before the start of the employment.

Salary and working conditions

You have to pay at least the minimum salary in the sector, as applicable to your other employees (or the minimum salaries on company level if more advantageous rules were agreed upon) to the student, unless the sector itself provides an exception for student work. For example, in JIC 200 (joint industrial committee for white-collar employees), specific minimum salaries are provided for students.

As a general rule, the same labour law rules are applicable to students as to a normal employee. For example, students also have to receive a copy of the working regulations when they start their employment.
However, there are some exceptions to this general principle. A student contract contains a trial period of 3 days, students may work less than 1/3 of the weekly working time (in a 38 hour week, this implies that students may work less than 13 hours per week) and night work is prohibited in most cases for minors.

Enrolment certificate

As an employer, you must be able to demonstrate that the person employed is actually a student. The NSSO therefore requires that you present the student’s enrolment certificate for the ongoing academic year upon their request.

Keeping that in mind, we highly recommend you to request the student to provide you with a copy of that enrolment certificate prior to the start of the employment and to keep this copy available at the company’s premises.

Extension quota 600 hours in 2023 for the healthcare sector

As indicated above, a student can work a maximum of 600 hours per calendar year with a lower solidarity contribution.

During the corona crisis, the government wanted to allow the use of job students to tackle the increased workload in the healthcare sector. Therefore, it was decided that the hours a student worked in the healthcare sector during among others the year 2022 would not count towards the quota. It was decided to extend these measures for the first quarter of 2023. Student work performed in healthcare during the first quarter of 2023 will thus not count towards the annual quota of 600 hours.

On an annual basis, some students will therefore be able to work more than 600 hours with the lower solidarity contribution. The other principles mentioned above remain valid (Dimona, a written student contract, etc).

What should you do as an employer?

Before the start of the student’s employment:

  • Request enrolment certificate and certificate Student@work
  • Sign student contract
  • Perform Dimona declaration – inform Pro-Pay!

Upon start of employment: give the student a copy of the working regulations and ask him or her to sign an acknowledgement of receipt.

The new purchasing power premium

The new purchasing power premium

We already informed you that the maximum margin for wage cost development (wage norm) for 2023 – 2024 has been set at 0%, which means that wages cannot increase on top of indexations and scale increases. This wage norm also serves as a framework for the biennial sectoral and enterprise wage negotiations.

Since there are companies that have achieved very nice results in 2022 and want to grant their employees something extra, the government has now created a new premium, the purchasing power premium.


What is it about?

The purchasing power premium can be granted by employers who have achieved a high profit or an exceptionally high profit in 2022.

The terms “high profit” and “exceptionally high profit” were not defined by the government. It now falls to the sectors to define these terms during the currently ongoing sector negotiations.

Once determined by the sector, companies that have achieved a “high profit” or an “exceptionally high profit” will have to/will be allowed to grant this premium according to the modalities determined by the sector.

There will only be a possibility to grant this premium to employees through an individual agreement if the sectors do not have any arrangement regarding the premium.

! As negotiations are currently in progress in the various sectors, we recommend that you do not proceed with the allocation of this premium for the time being, but wait for the end of the negotiations. Indeed, as a company, you risk a requalification of the premium into a gross wage benefit if you do not meet the conditions of the sectoral collective labour agreement.

This premium is allocated in the form of consumption vouchers and amounts to maximum € 500 for companies with a “high profit” and maximum € 750 for companies with an “exceptionally high profit”. Whether this amount or a lower amount is granted is also part of the negotiations in the sectors.

The purchasing power premium is exempt from taxes and social security contributions for the employee. The employer will have to pay a special employer social security contribution of 16,5%. This premium is deductible as a professional expense.

The premium can be granted from 1 June 2023 until 31 December 2023 and can be spent until 31 December 2024.

We will keep you further updated as soon as we have more news.

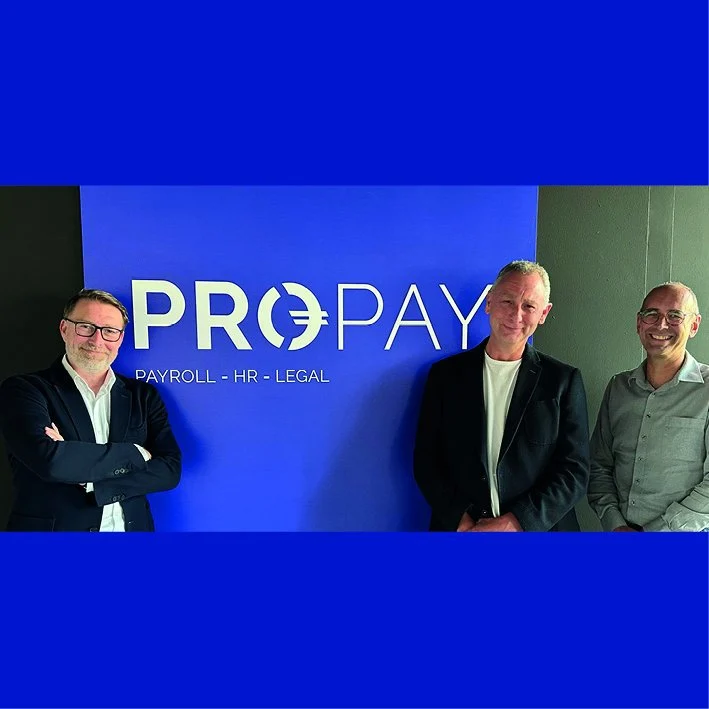
David Alen takes over the torch from Geert Van Hoye as CEO of Pro-Pay

David Alen takes over the torch from Geert Van Hoye as CEO of Pro-Pay

(from left to right: David Alen, Geert Van Hoye, Erik Van den Eynde)

After 22 years, Geert Van Hoye, founder of Pro-Pay, is stepping down as CEO to become chairman of our Board of Directors. David Alen, who has worked very closely with Geert as a partner for many years, will take over his role. Erik Van den Eynde succeeds David Alen as Chief Operations Officer.

“I have full confidence in David. He understands our vision, and the commitment we make to our customers as well as our employees. More than that, he has helped outline every step in the process himself.” – Geert Van Hoye

Over the last 30 years, Pro-Pay has grown from a start-up with a mission into a thriving company with more than 45 employees and customers all over the world. We have been and continue to be committed to innovation and strong technology.

“This evolution comes as no surprise at all to the Pro-Pay team, and therefore has no impact whatsoever on our operation. We have great, dedicated staff and guarantee continuity for our customers.” – Geert Van Hoye

Geert remains in the picture at Pro-Pay. As chairman of the Board of Directors, he is actively working to ensure a smooth transition, and continues to help build the success of our company.

Adjustment mileage allowance as from 1 April 2023

Adjustment mileage allowance as from 1 April 2023

Employees who use their own car to travel for professional purposes, can receive a reimbursement from their employer for the costs incurred.

It is not necessary to be able to prove the exact amount of these costs as the authorities have fixed a maximum lump sum per kilometre that is accepted as a cost proper to the employer (“mileage allowance”). This mileage allowance is exempt from social security contributions and taxes if the maximum amount per kilometre is not exceeded.

As you could read in our newsletter of 16 December 2022, the mileage allowance is no longer indexed annually, but quarterly. The new amount applicable starting from 1 April 2023 until 30 June 2023 is € 0.4246 per kilometre.

As a reminder: the amount that was applicable from 1 January 2023 until 31 March 2023 was € 0.4259 per kilometre. Note that there is a decrease compared to the previous amount.

An additional condition is that the number of kilometres per year should not be abnormally high (max. 24,000 kilometres per year). If the number of kilometres is higher, proof must be furnished.

This amount is a maximum amount. Employers can reimburse the driven kilometres at a lower rate without any discussion. A higher reimbursement is also possible, but in that case, the burden of proof lies with the employer and the employee. They should be able to prove that the allowance granted is in line with the actual cost.

Adjustment of the reimbursement of business trips abroad

Adjustment of the reimbursement of business trips abroad

The costs that the employee incurs during business trips abroad can be reimbursed on a lump-sum basis by the employer. The accepted lump-sum amounts in the so-called ‘country-list’ were adjusted on 15 February 2023. We will discuss the modalities of granting such allowances for business trips in this newsletter.

What are business trips abroad?

There are two categories of business trips abroad:

  • Category 1 “short business trips abroad”: an employee resides abroad in the service of the employer during a period of minimum 10 hours and maximum 30 calendar days;
  • Category 2 “long business trips abroad”: an employee resides abroad in the service of the employer during a period longer than 30 calendar days.

! The employees concerned must be primarily engaged in a sedentary professional activity.

Which reimbursements exist and what costs do they cover?

Lump-sum reimbursements are meant to cover small costs, which the employee incurs during his business trip. The costs that are covered are among others: lunch and dinner costs, snack and drinking costs, local transport costs and telephone communication services. The employee does not have to provide (written) proof of these costs. The amount is a fixed lump sum.

Hotel, travel and fuel costs are not covered. These costs can of course be reimbursed upon presentation of written proof in such forms as tickets and vouchers. Accommodation costs may also be reimbursed on a lump-sum basis, but this is less common in practice.

There are two types of acceptable lump sums:

  • A lump-sum reimbursement of 37.18 €/day, regardless of the destination and duration of the business trip (categories 1 and 2).
  • A lump-sum reimbursement according to a country-list. This country-list defines the accepted lump-sum reimbursements by country and by category. The amounts on the country-list are usually higher than the flat rate amount of 37.18 €/day. The country-list is meant to be adjusted every year, but the last adjustment dates back to 2018. The new adjusted amounts were announced on 15 February 2023. You can consult them via this link.

Conditions

The costs may only be included in the lump-sum reimbursement if these expenses are not already reimbursed based on expense reports and if the employee does not report it as a business expense in his tax return.

In addition, the following conditions apply:

  • The amounts can be used for each full day of absence (= a day between two overnight stays during the business trips) and for business trips where the employee returns the same day but has been absent for more than 10 hours.
  • For trips lasting more than 24 hour, the amount should be reduced by 50 % for the days of departure and arrival.
  • If the employer already pays meal expenses, the daily allowance is reduced by 35% for lunch and 45% for dinner.

Under the conditions explained in this newsletter, lump-sum daily allowances are costs proper to the employer. The tax authorities therefore accept that these allowances are exempt from tax and we expect the NSSO will also apply this reasoning regarding the exemption of social security contributions.

! The lump sum amounts are maximum flat rates. You are free to grant a lower lump sum or alternatively reimburse these costs based on supporting documents.

Modifications regulations time credit

Modifications regulations time credit

From February 1, 2023 a number of changes have entered into place for employees who apply for a time credit from that date.

The changes only concern the right to allowances. The right to obtain a time credit – without allowances if need be – does not change. Time credit “landing positions – end of career” does not change either.

In this newsletter, we inform you of these changes.

Time credit for reasons of “care taking for a child”

  • In case of full time time credit: the age of the child for whom the employee can take time credit will be reduced from 8 years to 5 years from 1 February 2023. The employee’s child may therefore be a maximum of 5 years old at the time of the start of this full-time suspension.

! The age of 8 years is maintained for half-time or 1/5 time credit with allowances.

  • The right to allowances will be reduced from 51 months to 48 months from February 1, 2023 for the time credit “caring for a child” for all possible suspensions (full-time, half-time and 1/5). This means that it is possible to receive 51 months of time credit for the reason “caring for a child”, but that the employee can only receive allowances for 48 months. This provision also applies to an employee who has already taken time credit before February 1, 2023, but who has not yet taken 30 months of thistime credit on February 1, 2023.
  • From June 1, 2023, the employee will also have need a seniority with the employer of 36 months instead of the current 24 months to be entitled to allowances. This new seniority condition does not apply when the time credit is taken immediately following the parental leave.

All suspensions of time credit for a reason

In addition to time credit “caring for a child”, there are other forms of time credit for a reason, such as following a recognized training and caring for a seriously ill family member.

The following changes apply to all forms of time credit with allowances, including the reason “caring for a child”:

The seniority condition with the employer is increased:

  • for a full-time time credit, the employee must be employed full-time during the 12 months preceding the written notification to the employer or part-time during 24 months.
  • for a half-time time credit, the employee will have to be employed full-time during the 12 months preceding the written notification to the employer instead of the current ¾ employment.
  • nothing changes for the 1/5 time credit: full-time employment was already required here.

The maximum period remains 51 months for the other time credits for a reason – except for the reason “caring for a child” (48 months) and the reason “following a recognized training” (36 months).

The increased allowances for full-time and half-time time credit for employees who have at least 5 years of seniority with the employer will be abolished.

On the other hand, from July 1, 2023, some allowances will be increased (thematic leave for the care of a child and 1/5 time credit for a reason) for single employees with children.

Thematic leaves

Employees older than 50 years received an increased allowance in the framework of a thematic leave (parental leave, medical assistance leave, palliative leave). These increased benefits will be abolished.

Points of action

  • Make sure that your employee who applies for time credit carefully checks whether he/she meets the new conditions so that he/she is entitled to time credit with allowances.
  • Make an annex to the employment contract in order to record the new work schedule and the (possible) impact on the other employment conditions.

Do not hesitate to contact us for more information through legal@pro-pay.be.

Right to de-connect: modify your working regulations

Right to de-connect: modify your working regulations

Last year we informed you about the new right to deconnection in a newsletter.

Because of this, employers who employ 20 or more employees are obliged to work out the following three modalities in the working regulations or a company CLA at the latest by 1 January 2023:

  1. The practical modalities of the employee’s right not to be available outside his or her working schedule.
  2. The guidelines for the use of digital tools so that the employee’s rest periods, holidays, private and family life are safeguarded.
  3. Training and awareness-raising actions, both for employees and managers, on the wise use of digital tools and the risks associated with excessive connection.

However, the FPS Work (“Federal Public Service Employment, Labour and Social Dialogue”) communicated that employers were given a 3-month extension. Therefore, the modified working regulations must be in place at the company no later than 1 April 2023.

! Action point

Check if you have to change you working regulations. Please note that in the context of the Labour Deal, other measures also have to be compulsorily included in the working regulations (or company CLA), regardless of the number of employees in the company.

Contact our Legal Team legal@pro-pay.be for more information.

Mandatory bicycle allowance as from 1 May 2023

Mandatory bicycle allowance as from 1 May 2023

As of 1 May 2023, all private sector employees who cycle to work will be entitled to a bicycle allowance. Until now, this was not the case in all sectors. A more general right to a bicycle allowance has now been established in a new collective labour agreement, CLA no. 164. In this newsletter, we discuss what impact this has and to which companies this new national CLA applies.

Which allowance?

In order to encourage commuting by bicycle, the National Labour Council has decided that employees of the concerned companies are entitled to a bicycle allowance of € 0.27 per kilometre as from 1 May 2023.

This allowance is exempt from social security contributions and taxes and will be indexed annually. The employer must grant a bicycle allowance up to a maximum distance of 40 kilometres per day (20 kilometres there and 20 kilometres back).

Which companies?

The national CLA no. 164 applies in principle to all companies but is supplementary. This means that existing sector and company CLA’s that already grant a specific bicycle allowance will continue to apply.

There are several sectors and enterprises that have already concluded CLA on this subject. These existing CLA’s on bicycle allowances will remain unchanged by the introduction of this new CLA, even if the bicycle allowance is lower than € 0.27 per kilometre. For example, the lower bicycle allowance of the Supplementary Joint Industrial Committee 100 for blue-collar workers and 200 for white-collar workers will continue to apply.

There is also a transitional provision for joint industrial committees that were established for the first time since 1 January 2020, such as Joint Industrial Committee 335. Employers in this JIC should not yet grant this allowance between 1 May 2023 and 31 December 2023, in order to give the sector time to conclude its own sectoral CLA on this matter.

Conditions

In order to be entitled to the bicycle allowance, the employee must use the bicycle regularly for commuting. For example: the employee cycles to work once a week, or the employee cycles to work daily during a certain period.

Of course, the same (part of a) journey cannot be reimbursed twice. For example, if an employee already has a full-time annual train season ticket, he can no longer receive a bicycle allowance if he occasionally comes to work by bicycle for that same route.

Finally, the employee should sign a sworn statement stating the number of kilometres of the route and the number of days.

Action point

If it was not compulsory in your sector to give a bicycle allowance until now, you will as a rule have to do so from 1 May 2023. In that case, ask your employee who regularly travels by bicycle to sign a sworn statement and inform your Payroll Business Partner monthly about the bicycle allowance.

Adjustment mileage allowance as from 1 January 2023

Adjustment mileage allowance as from 1 January 2023

Employees who use their own car to travel for professional purposes, can receive a reimbursement from their employer for the costs incurred.

It is not necessary to be able to prove the exact amount of these costs as the authorities have fixed a maximum lump sum per kilometre that is accepted as a cost proper to the employer (“mileage allowance”). This mileage allowance is exempt from social security contributions and taxes if the maximum amount per kilometre is not exceeded.

As you could read in our newsletter of 16 December 2022, the mileage allowance is no longer indexed annually, but quarterly. The new amount applicable from 1 January 2023 to 31 March 2023 is € 0.4259 per kilometre.

As a reminder: the amount that was applicable from 1 October 2022 until 31 December 2022 was € 0.4201 per kilometre. Note that there is an increase compared to the previous amount.

An additional condition is that the number of kilometres per year should not be abnormally high (max. 24,000 kilometres per year). If the number of kilometres is higher, proof must be furnished.

This amount is a maximum amount. Employers can reimburse the driven kilometres at a lower rate without any discussion. A higher reimbursement is also possible, but in that case, the burden of proof lies with the employer and the employee. They should be able to prove that the allowance granted is in line with the actual cost.